
Key Takeaways
- From 15 September 2026, borrowers get a three-business-day cooling-off period on unsecured non-business loans.
- If you cancel a personal loan in time, you repay the principal you received plus a capped fee, with no interest.
- The fee is capped at S$50 for a principal of up to S$5,000, or at 3.5% of the principal for a principal above S$5,000.
- Under the licensed money lender new rules, the 4% monthly interest cap and the other existing limits such as the loan approval fee cap still apply to any loan you keep.
If you have heard that the licensed money lender new rules have changed how borrowing works, you heard right.
Since 15 September 2026, every borrower who takes an unsecured, non-business loan from a licensed money lender in Singapore gets a short window to cancel once the loan is paid out, so you no longer have to decide on the spot.
At 111 Credit, we want you to know exactly how the cooling-off period in Singapore works before you sign anything. This is why we created this guide to walk you through what changed, what cancelling costs, what is enforced, which loans are covered and which limits still apply, all in plain language.
What Changed Under the Licensed Money Lender New Rules
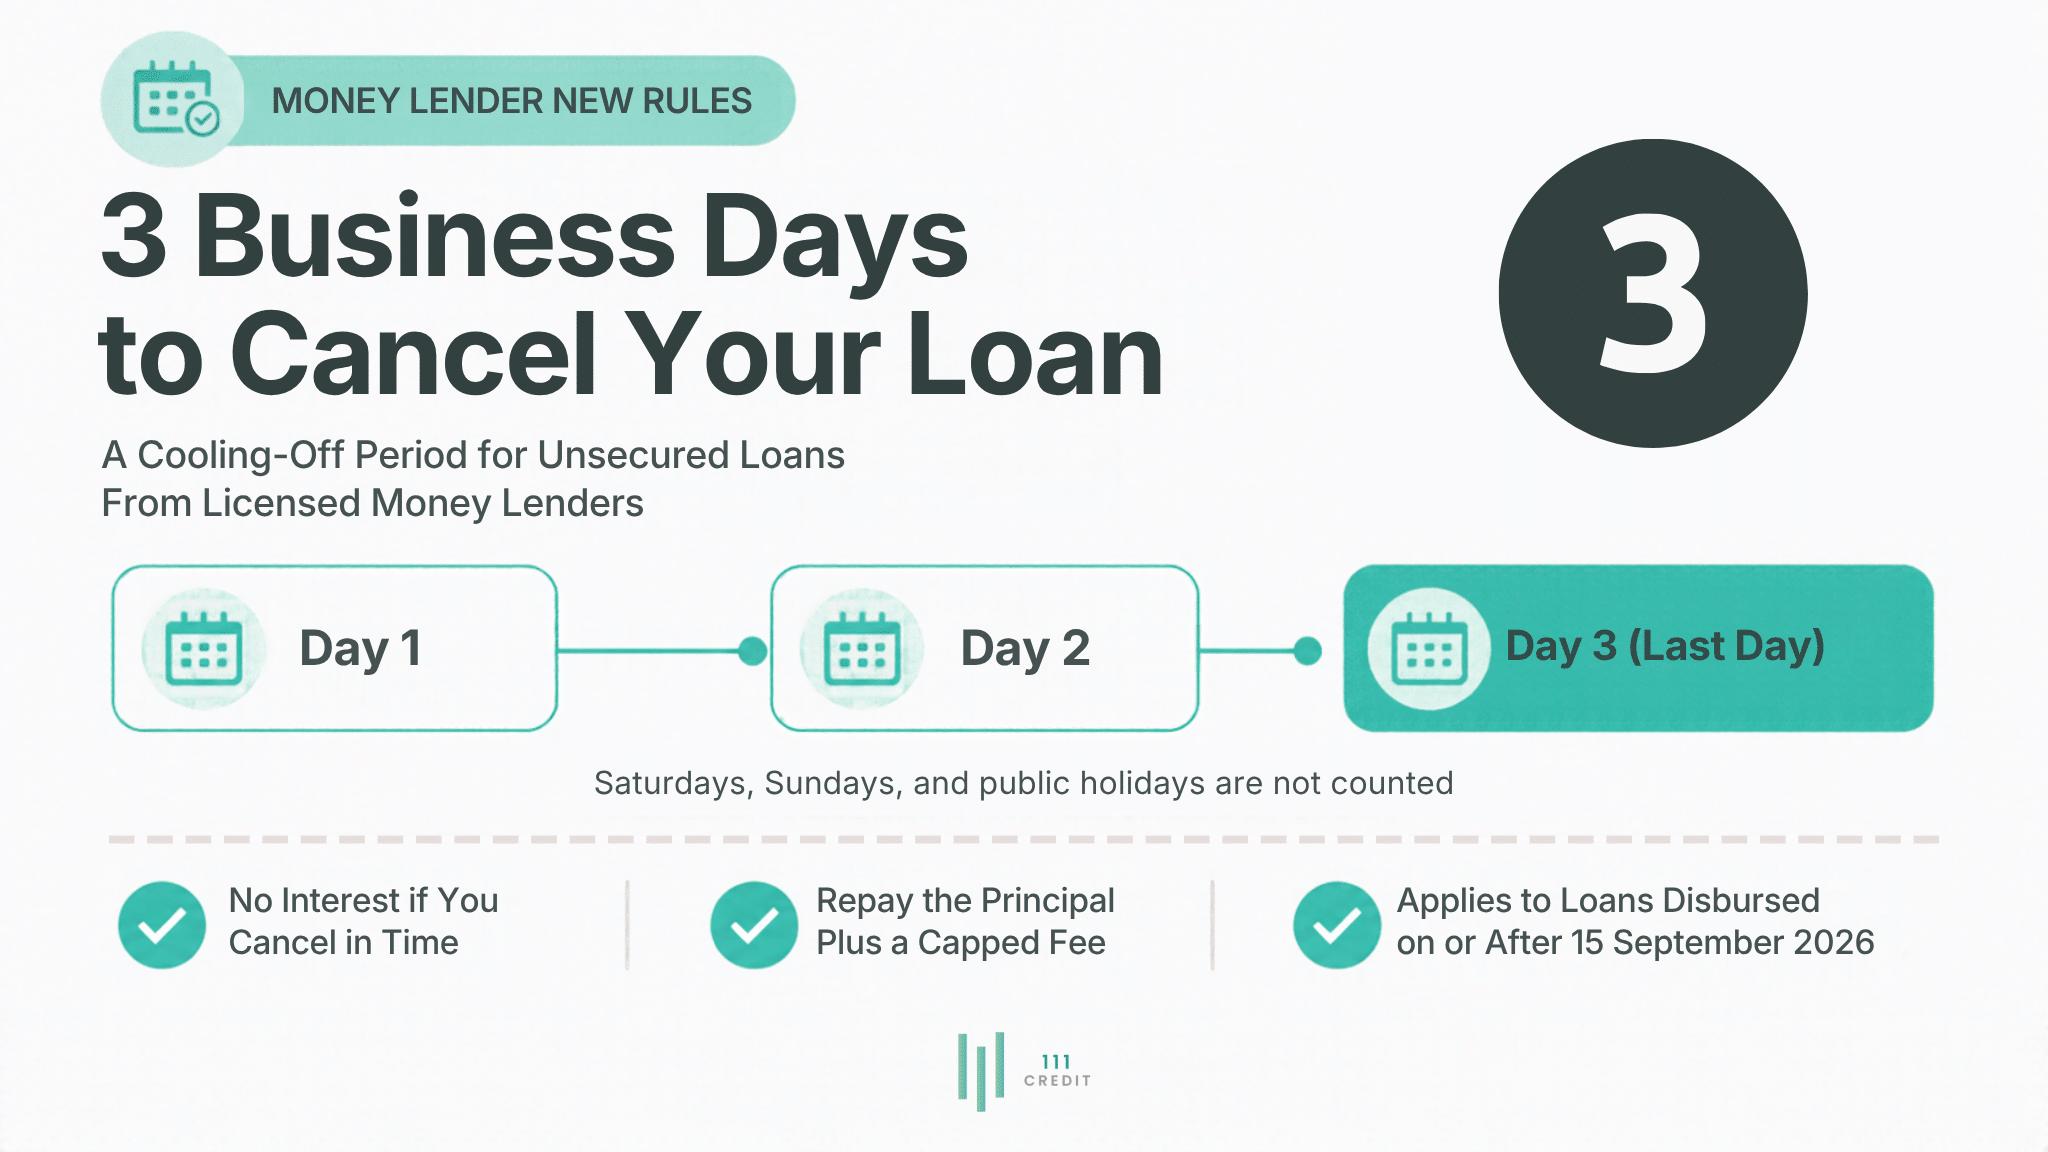
The biggest change you need to know about is the mandatory cooling-off period.
Before 15 September 2026, a lender could keep the full approval fee and any interest accrued if you cancelled a loan. Now you have three business days from the day your loan is paid out to change your mind, with a cap on what you repay.
The table below shows the difference before and after.
| Changes That Affect You | Before 15 September 2026 | From 15 September 2026 |
|---|---|---|
| Cancelling a loan | No mandatory cooling-off period | Three business days after the loan is paid out, excluding the disbursement date |
| Cost of cancelling | Lender could keep the full approval fee and any interest accrued | Repay amount disbursed with a capped portion of approval fee, no interest |
| Loans covered | No mandatory cooling-off period applies | Unsecured non-business loans |
How the Cooling-Off Period Works: A Step-by-Step Guide
If you change your mind about your loan, how do you cancel a personal loan in practice under the licensed money lender new rules?
Follow these steps:
- Sign your loan contract and keep a copy for your records.
- Once the loan is paid out to you, decide within three business days whether you still want it. The day it is paid out does not count!
- Tell your lender that you wish to cancel, and keep a record of when you did. Lenders must allow you to cancel as long as you do so within the three business days.
- Repay the principal you received plus the capped fee. No interest is charged.
- Ask for confirmation that the loan has been cancelled.
Use this time to compare repayments, ask questions and check that the loan suits your budget. For more information, see the Registry of Moneylenders’ borrowing guide.
What You Pay if You Cancel During the Cooling-Off Period
If you cancel within 3 business days, money lenders cannot charge you any interest. You repay the principal you actually received plus a capped fee. The fee cannot be more than S$50 for a principal of up to S$5,000, or 3.5% of the principal for a principal above S$5,000. It also cannot be more than the approval fee you were charged.
The table below works through two loans adapted from the Ministry of Law’s illustrations, so you can see what each one would cost you if you used the cooling-off period.
| You borrow | Approval fee | You receive | If you cancel, you repay at most |
|---|---|---|---|
| S$1,000 | S$100 (10% of S$1,000) | S$900 | S$950 (S$900 + S$50 fee cap) |
| S$10,000 | S$200 (2% of S$10,000) | S$9,800 | S$10,000 (S$9,800 + S$200 fee) |
In both cases listed above, cancelling costs you only the fee and never any interest: S$50 on the smaller loan and S$200 on the larger one.
Which Licensed Money Lender Loans Do the New Rules Cover?
The cooling-off period in Singapore applies to unsecured non-business loans disbursed on or after 15 September 2026. This includes personal loans, monthly loans, payday loans, instant loans and more from licensed money lenders in Singapore.
Business loans sit outside it, so check the type of loan you are signing before you rely on this window. To work out what suits your budget, see our guide on how much you can borrow.
Money Lender Regulations: Moneylenders Act Caps That Still Apply
The new rules do not change the existing caps on interest, fees and total charges. The cooling-off period sits alongside the money lender regulations you already know.
If you keep your loan, the Moneylenders Act still protects you. Interest is capped at 4% per month, and the approval fee cannot be more than 10% of the principal. Late fees are capped at S$60 per month, and interest, late fees and the approval fee combined can never exceed the amount you borrowed. Read our guide to the 4% monthly interest cap for the full picture.
Before You Sign: Always Verify a Licensed Money Lender in Singapore
These rules bind every licensed money lender in Singapore, and unlicensed money lending is illegal, so confirm the licence first. Run through this checklist before you sign:
- Search for the lender on the official list of licensed money lenders from the Registry of Moneylenders.
- Read the contract for the interest, fees and cooling-off terms.
- Keep copies of everything you sign, and ask about anything unclear.
Conclusion: Know the Licensed Money Lender New Rules Before You Borrow
The licensed money lender new rules give you three business days to cancel an unsecured non-business loan, at the cost of only the principal you received and a capped fee. The existing Moneylenders Act caps still apply if you go ahead.
As a licensed money lender at Lucky Plaza in Orchard, we believe that borrowing should feel safe and clear. Rest assured that we explain every fee and repayment term in plain language before you sign. Read our client reviews to hear from other borrowers. If you are uncertain about your loan status or if you can cancel, feel free to contact us with any questions, learn more about 111 Credit or apply online to submit your application!
FAQs about the cooling-off period for licensed money lenders
Is the cooling-off period three calendar days?
No, it is three business days counted from the day after your loan is paid out. Weekends and public holidays are not counted. Confirm the exact deadline with your lender when you sign.
Do I pay interest if I cancel during the cooling-off period?
No, you repay only the principal you received plus the capped fee. The fee also cannot be more than the approval fee you were charged, so the total you repay never goes above the amount you borrowed.
Do the new rules cover business loans?
No, the cooling-off period applies to unsecured non-business loans. If you are unsure which category your loan falls into, ask your lender before you sign.
What happens if I miss the cooling-off period?
Your loan carries on under the terms you signed, and the existing caps still protect you. If you have any questions about your contract, feel free to ask us, and we will walk you through it.
Read these next: